
Beauty Equipment Rental, Instalments or Cash: Payments and Contracts
Rental, instalments and cash differ beyond the initial payment. Compare the same period's complete payments, ownership, maintenance, obligations during downtime and early exit. The examples below help organise quotes; they do not recommend financing or promise equipment will pay for itself.
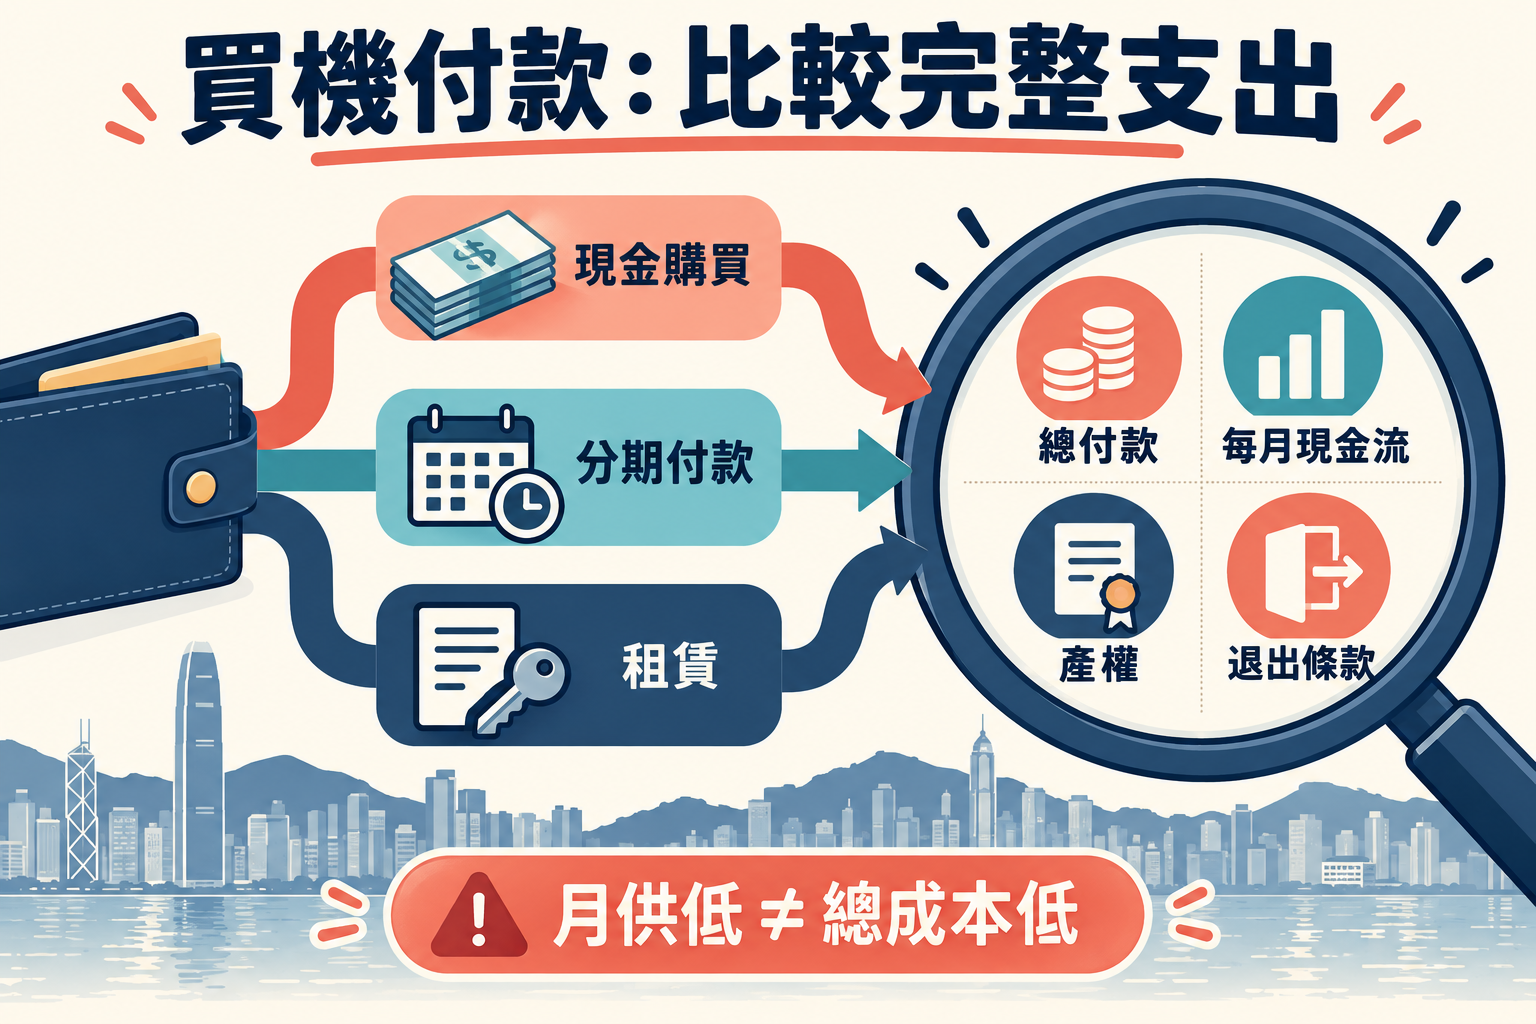
This AI-generated framework has Traditional Chinese labels and does not represent an offered Asia Pacific Beauty payment plan.
Examine what the contract actually provides
| Structure | Check | Do not assume |
|---|---|---|
| Cash purchase | Complete delivery price, milestones, acceptance, warranty | There are no later costs |
| Instalments or hire purchase | Deposit, payments, fees, ownership and default | Full ownership before final payment |
| Rental | Minimum term, deposit, repairs, return and buyout | Automatic ownership at the end |
“Monthly payments” may describe supplier credit, third-party borrowing or hire purchase. Identify the contract holder, recipient of payments and support provider in writing. A low deposit alone does not permit comparison.
A hypothetical 24-month comparison
These teaching figures are not quotes and exclude tax, time value, residual value and uncertain repairs. Compare identical equipment and configuration.
| Example | Calculation | Total paid/payable | End ownership |
|---|---|---|---|
| Cash | HK$120,000 + HK$5,000 delivery/training | HK$125,000 | Confirm purchase terms |
| Instalments | HK$30,000 + 24 × HK$4,500 + HK$2,000 fees + HK$5,000 delivery | HK$145,000 | Confirm transfer terms |
| Rental | HK$8,000 non-refundable fee + 24 × HK$4,800 + HK$2,000 return | HK$125,200 | Assumes return, no ownership |
A separate hypothetical HK$10,000 refundable deposit increases initial cash needs. If fully returned, it is not final net spending; deductions change that result. The example does not establish a generally cheapest option.
The instalment example totals HK$20,000 more than cash. Similar rental payments still buy a different end position because no equipment asset remains under the stated assumption.
Stress-test monthly cash flow
Put equipment obligations alongside other fixed costs and consider normal, slow and downtime scenarios. For example, HK$4,500 payments plus HK$1,500 related fixed expenses equals HK$6,000. At a hypothetical HK$300 contribution per session, those two items need 20 sessions. Twelve contribute HK$3,600, leaving HK$2,400 uncovered.
This is neither whole-salon payback nor a demand forecast. Contribution must deduct relevant variable costs; a package's advertised price is not contribution. Check whether all payments continue during faults or rescheduling. See the ROI framework.
Check interest, fees and zero-interest wording
Request total payments, timing and every fee. For borrowing, obtain applicable APR information and calculation details from the financing provider. Monthly flat rates and annualised costs are different. IFEC loan information explains interest and related charges.
Zero interest may coexist with administration fees, lost cash discounts, insurance or required service charges. Do not assume immediate tax deductibility or a particular liability treatment; accounting and tax depend on the agreement and applicable rules.
Identify who services and who collects payments
Separate equipment supply, financing and maintenance responsibilities. A third-party loan obligation may continue when equipment fails. For rental, define repairs, wear, consumables, transport, replacement units and payments during downtime.
Warranty start dates, transfer and prescribed supplies may affect relocation or resale. Written answers support a meaningful cost comparison.
Ask about exit, relocation and transfer
- What minimum term and early-exit formula applies?
- Are early settlement fees or withdrawn rebates possible?
- Can the unit move, and who pays reinstallation?
- Can the agreement transfer, and whose consent is required?
- Is a rental buyout available at a defined price?
- What condition, inspection, cleaning and accessories are required on return?
- What happens if the supplier closes or the model is discontinued?
Frequently asked questions
Does a lower monthly payment mean lower cost?
No. Deposit, term, fees, end assets and exit conditions all matter.
Is rental always best for a new salon?
No. Demand, reserves, term, purpose and actual conditions differ.
Can payments stop when the unit fails?
Do not assume so. Check the contract and resolve obligations with the relevant parties.
Is a promise that session income covers payments sufficient?
No. Use conservative demand and actual costs, including a shortfall scenario.
Are these Asia Pacific Beauty's offered terms?
No. All figures are hypothetical; request an actual quote.
Next steps
Use the procurement process and used-unit checks. Obtain appropriate financing, legal, tax or accounting advice for the actual agreement.